
How Jensen Huang’s Exit Tests Nvidia’s $3.9 Trillion Empire
Jensen Huang’s departure from Nvidia has sent its shares lower and raised questions about the company’s future. Despite strong financial results, the leadership change puts its succession plans and long-term dominance in the AI industry under scrutiny.
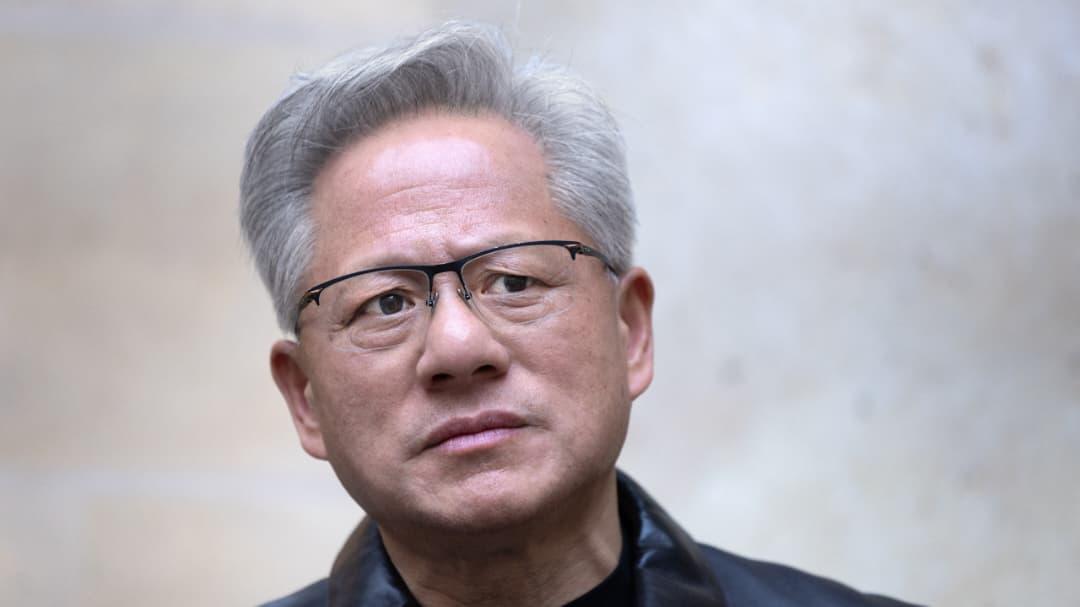
When a company valued at nearly $4 trillion loses its chief executive, the event is more than a leadership transition. It tests investor confidence in the people, technology and business model behind its extraordinary growth. Jensen Huang’s departure has sent Nvidia’s shares tumbling, exposing the risks of founder dependence and raising questions about whether the world’s most influential AI chipmaker can maintain its dominance without the man who built it.
Nvidia’s board accepted Huang’s resignation as president and chief executive on Wednesday, with the company announcing the decision on Thursday, November 12, 2026. Huang, 63, also gave up his board seat. His exit closes a 33-year run at the helm of the company he co-founded, which has become central to the global AI industry.
Why Huang stepped down
The resignation did not come out of nowhere. It followed revelations that Huang had two extramarital affairs, one of them with a woman accused of spying for China Jensen Huang's Affair. Huang admitted the first affair on the Sunday before his exit. It was reportedly with Alice Huang, a senior executive at Singapore-based data-centre company Mega speed, who is not related to him. US intelligence reportedly circulated a memo this spring alleging that she was an asset of China's Ministry of State Security. Beijing has rejected the spying allegations.
On Wednesday, The New York Times reported a second affair, with an Nvidia executive who reports to him. The board had announced an investigation into what it called a "foreign intelligence effort" targeting Huang, while saying at the time that it still had confidence in him. Nvidia shareholders have since filed a class action lawsuit against Huang and the company, alleging that information about the relationship was not disclosed to investors. Huang has also agreed to testify before Congress.
These are allegations and reports, not findings. The governance question for investors is whether the board acted fast enough once the issue surfaced.
The market reacts
The market reaction was immediate. Nvidia’s shares fell as much as 14% on Thursday before recovering some of their losses, eventually closing down 4.3% at $166.19. AMD and Broadcom each rose about 6% during the same session. The pressure carried into Friday, November 13, as investors reassessed the leadership outlook and the company’s exposure to the wider AI investment market.
At Thursday’s closing price of $166.19, Nvidia’s market capitalisation stood at roughly $4.01 trillion. By about 1:50 p.m. Eastern Time on Friday, the stock was trading at $164.61 per share, about 1% lower for the session. This put its market value at an estimated $3.975 trillion, below the $4 trillion mark.
The decline is even steeper when measured against the company’s peak. Nvidia reached a record closing price of around $243 per share, representing a market value of $5.78 trillion, in early October 2026. That leaves the company roughly $1.8 trillion below its high.
Following the decline from that October record, the stock trades at about 12 times expected earnings, its lowest valuation since 2012. The slide reflects broader market pressure and concerns about returns on AI spending, now compounded by the leadership news. The central question is how much of Nvidia’s value rests on its business fundamentals and how much depends on investor confidence in its founder.
What a $3.9 Trillion Valuation Means
Market capitalisation is the total value of a company’s publicly traded shares. It is calculated by multiplying the share price by the number of shares outstanding. With about 24.15 billion shares and a price of $164.61, Nvidia’s market value comes to roughly $3.98 trillion.
That figure is not revenue, cash, total assets or profit. It represents what investors collectively value the company’s equity at. A drop in market capitalisation also does not mean an equivalent amount has disappeared from Nvidia’s bank accounts. Rather, it means investors are assigning a lower value to the company’s future prospects.
What Supports the Valuation
Despite the turbulence, Nvidia’s underlying business remains large and highly profitable. Its second-quarter fiscal 2027 results, covering the three months ended July 26, 2026, show the financial engine behind its valuation:
Revenue: $96.22 billion, up 106% from a year earlier and 18% from the previous quarter.
Gross profit: $72.14 billion, representing a GAAP gross margin of about 75%.
Operating income: $63.73 billion.
GAAP net income: $59.69 billion, or $2.46 per share.
Free cash flow: About $21.34 billion.
The Data Centre division generated $89 billion, up 117% year on year. That represents about 92.5% of quarterly revenue, showing how heavily demand for AI computing infrastructure drives Nvidia’s expansion.
For the first six months of fiscal 2027, revenue reached $177.84 billion, compared with $90.81 billion during the same period of the previous year. Nvidia also returned about $26 billion to shareholders through share buybacks and dividends during the quarter, with roughly $99 billion remaining under its share repurchase authorisation.
These figures show a valuation backed by an exceptionally profitable and fast-growing business, rather than AI speculation alone. However, the concentration of revenue in Data Centre also creates exposure. A slowdown in spending by major cloud providers, AI developers or technology companies could significantly affect future growth.
Beyond Chips: The Ecosystem Behind Nvidia’s Dominance
Nvidia’s advantage goes well beyond manufacturing graphics processing units (GPUs). Its CUDA software platform, networking technology, specialised processors and integrated computing systems form an ecosystem on which many developers and enterprises already depend.
Its GPUs are used to train and run AI models, while its networking technology and computing systems connect thousands of processors to build large-scale AI infrastructure.
This creates significant switching costs for customers. Moving to another supplier can require changes to software, infrastructure, development processes and existing technical investments. Nvidia’s position therefore depends not only on the performance of its processors but also on how deeply its technology is embedded in customers’ operations.
The next-generation Vera Rubin platform is intended to strengthen that position. It has begun production shipments and is expected to account for about 20% of third-quarter Data Centre revenue. Maintaining its lead will still require sustained investment in research and development, manufacturing capacity, strategic partnerships and reliable execution.
The Leadership Question: Can Nvidia Operate Without Huang?
Huang’s exit is a major test of Nvidia’s succession planning. For more than three decades, he has been the central figure in the company’s strategy, technological transformation and relationships with key industry players. His leadership took Nvidia from graphics and gaming into the infrastructure powering the global AI industry. He had repeatedly avoided naming a successor when the question was raised.
Longtime Chief Financial Officer Colette Kress has become interim chief executive and will retain her CFO role while the company searches for a permanent successor. The board has appointed Harvey Jones, a former chief executive of chip-design software firm Synopsys, as its first-ever chair.
Kress has deep institutional knowledge, having served as CFO since 2013 after nearly 25 years in finance roles at companies including Cisco and Microsoft. However, overseeing a company’s finances is different from directing its overall technology and commercial strategy.
The board says it has full confidence in Kress and the leadership team, and expects operations, customer commitments and the product roadmap to continue without interruption. Investors will want to see evidence of that across product development, customer relationships, capital allocation and the company’s long-term AI infrastructure strategy.
The stakes are high because Nvidia’s valuation already assumes continued growth. Any uncertainty about the company’s ability to execute its strategy could therefore affect its share price.
Wall Street’s Early Verdict
Analysts have been divided over the leadership change. Truist and Craig-Hallum both downgraded their ratings to Hold on Thursday. Truist argued that the risks now extend beyond the CEO’s departure to include Nvidia’s corporate culture and whether its chips reached buyers in China. DA Davidson maintained its Buy rating, saying Kress is capable of handling the role.
There is also a potential shareholder overhang. Huang held about 811.5 million Nvidia shares as of September, a stake worth roughly $133 billion at current prices. Any indication that he intends to sell could put additional pressure on the stock, and investors will be watching his filings closely.
Opportunity for Rivals
The turmoil could create opportunities for Nvidia’s competitors. Advanced Micro Devices (AMD) and Broadcom are among the companies positioned to benefit if customers diversify their AI computing infrastructure.
AMD continues to develop its Instinct accelerator portfolio, while Broadcom has strengthened its position in custom AI chips and networking. Other technology companies are also developing their own processors to reduce their reliance on Nvidia.
However, capitalising on the moment will not be easy. Nvidia’s developer ecosystem, integrated hardware and software, and relationships with major cloud providers give it an advantage that a change in leadership alone will not erase.
The real question is whether rivals can use the uncertainty to accelerate customer diversification and win a larger share of future AI infrastructure spending.
The Next Financial Test
Nvidia’s third-quarter fiscal 2027 results, due on November 17, will provide the next measure of its performance. The company has confirmed that it will report as scheduled. It previously guided for quarterly revenue of about $108 billion, plus or minus 2%, excluding any Data Centre compute revenue from China.
Investors will watch whether demand for its AI computing products is strong enough to support that outlook. They will also be assessing several other factors:
Margins: Management expects gross margin of about 74% in the third quarter, falling to 71–72% in the fourth quarter because of rising memory costs.
Commitments: Purchase commitments rose from $119 billion to $279 billion in a single quarter, mainly for memory. Nvidia has also committed up to $105 billion in guarantees to help OpenAI lease a data centre.
Customer concentration and export restrictions: These remain important risks as competition intensifies.
Management’s tone: This will be the first earnings call without Huang, and investors will look for any change in how the company describes demand and its strategy.
The second-quarter results show that Nvidia remains highly profitable. The leadership shake-up should therefore not be mistaken for evidence that its operations have suddenly deteriorated. Instead, the market is reassessing the risks attached to the company’s future direction.
What This Means for Readers
For Nvidia shareholders: The company’s operating results remain strong, but its share price now reflects governance and succession risks as well. The November 17 earnings report will provide the first major indication of how the business is holding up during the transition.
For those following the wider AI market: Nvidia’s chips underpin much of the sector’s growth, so significant developments at the company can affect cloud, server and semiconductor stocks.
For those following corporate governance: The episode shows how a company can become dependent on one individual and how costly an unplanned leadership transition can be.
Can the Empire Outlast Its Founder?
Nvidia’s valuation rests on the expectation that artificial intelligence will continue transforming businesses, industries and global computing infrastructure. Its products are already central to that shift, and its financial results demonstrate the scale of demand.
Even so, a company of this size cannot rely indefinitely on one individual. Retaining experienced executives, sustaining innovation, managing financial commitments and preserving customer confidence will determine how well Nvidia handles the transition.
For investors, the immediate question is not simply whether Nvidia can recover the value it has lost. It is whether the company can demonstrate that its competitive advantage is institutional, technological and financial, rather than dependent on its founder.
At nearly $4 trillion, the stakes are considerable. The next chapter will show whether the business Jensen Huang built has the leadership strength and operational resilience to stand on its own.
Read our editorial standards and corrections policy.